Supreme Court 7-Judge Bench Holds Reference On States' Power For Additional Levy On Sales Tax Academic After GST
Amisha Shrivastava
4 Nov 2026 11:18 AM IST
The Court held that the reference has been rendered infructuous.
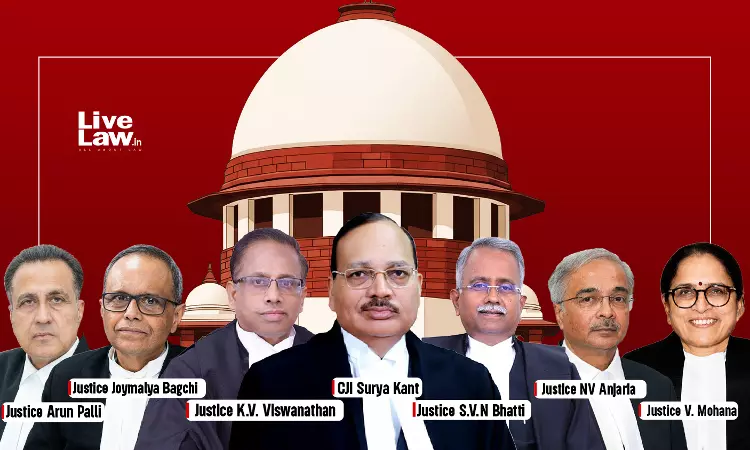
A seven-judge Constitution Bench of the Supreme Court, headed by Chief Justice of India Surya Kant, on Wednesday held that a nearly three-decade-old reference on the legislative competence of states to impose additional sales tax or surcharge calculated on existing sales tax has become academic following the introduction of the Goods and Services Tax (GST) regime.
The Constitution Bench comprising Chief Justice Surya Kant, Justice KV Viswanathan, Justice SV Bhatti, Justice Joymalya Bagchi, Justice NV Anjaria, and Justice V Mohana was answering a reference arising from Arjun Flour Mills, which concerned Odisha's levy of additional tax at 10% and 15% depending on dealers' annual turnover. The core constitutional question was whether such a levy fell within the states' taxation powers under Entry 54 of List II of the Seventh Schedule (as it then stood) or encroached upon Parliament's power to tax income.
Pronouncing the order, CJI Surya Kant said the issue related to the competence of state legislatures to levy a tax on the sale or purchase of goods under the then Entry 54 on the sales tax payable by a dealer rather than directly on his turnover. The bench examined the entire case law beginning with India Cement, Kodar, the statutory schemes of Odisha and Punjab, and the Punjab Social Security aspect, before turning to the constitutional framework on taxation and the new GST regime that rendered the earlier Acts and statutes redundant.
The Court summarised its conclusions as follows: the reference stemmed from a perceived conflict between Hoechst Pharmaceuticals and India Cement. India Cement dealt with a cess on royalty in a field covered by the Mines and Minerals (Development and Regulation) Act and did not hold that a levy computed as a percentage of another tax is, for that reason alone, beyond legislative competence. In principle, such a levy as an increment to an existing tax is to be judged in the same way as that tax. The premise in India Cement that royalty is a tax has since been overruled by a larger bench in Mineral Area Development Authority.
Consequently, there is no subsisting decision of the Court in conflict with the earlier view. The Court clarified that an additional tax or surcharge computed as a percentage of the sales tax payable is an enhancement of the rate of sales tax and remains a tax on the sale or purchase of goods within the then Entry 54 of List II. That distinction continues to hold good.
However, the constitutional entry and the state enactments under which the impugned levies were imposed have since been substituted or replaced by the GST regime.
"The constitutional entry and the state enactments under which the impugned levies were imposed have since been substituted or replaced, and the question referred to is of no prospective significance. Consequently, the question referred does not survive for adjudication by a 7-judge bench, and the reference has been rendered academic. In light of these conclusions, we deem it appropriate accordingly to direct that the reference is answered as having been rendered infructuous."
The bench left open specific questions concerning the validity of the surcharge under the Punjab General Sales Tax Act, 1948 (insofar as it required industrial units otherwise exempted from sales tax to pay the surcharge) and whether proceeds of the cess under the Punjab Social Security Act, 2000, could be credited directly to the Punjab Social Security Fund without first forming part of the Consolidated Fund of the State under Article 266. All other contentions of the parties in the individual matters, including those relating to assessments and consequential reliefs, were also left open. The Registry was directed to list the lead matter and connected matters before an appropriate regular bench for disposal in accordance with the observations.
In a separate opinion, Justice K.V. Viswanathan examined the perceived conflict between Hoechst and Kodar (and the role of India Cement) and held that Kodar was correctly decided and continues to be good law. He found no conflict between Kodar and Hoechst, noting that India Cement involved qualitatively different issues and legislative entries and could not be relied upon to undermine the holding in Kodar. The additional sales tax, determined with reference to the sales tax payable by a dealer whose annual turnover exceeds a minimum threshold and where there is no pass-through to consumers, is traceable to Entry 54 of List II as a tax on sale of goods and is not ultra vires as a tax on the income of the dealer.
The 27-year-old reference thus stands disposed of as academic in light of the GST regime that has fundamentally altered the constitutional and statutory landscape of indirect taxation in India.
The seven-judge Constitution Bench, headed by Chief Justice of India Surya Kant, had reserved its verdict on September 22, 2026, after examining the interplay between earlier decisions, including S Kodar v State of Kerala, Hoechst Pharmaceuticals Ltd v State of Bihar and India Cement Ltd v State of Tamil Nadu.
Background
The reference originated in Arjun Flour Mills v. State of Odisha, which challenged Section 5A of the Odisha Sales Tax Act, 1947. The provision, introduced in 1997, imposed an additional tax of 10% on dealers with an annual turnover between Rs 10 lakh and Rs 1 crore, and 15% on dealers whose turnover exceeded Rs 1 crore.
The dispute arose against the backdrop of conflicting judicial pronouncements on whether an additional levy calculated with reference to sales tax could independently fall within the State's legislative competence under Entry 54 of List II of the Seventh Schedule to the Constitution (taxes on the sale or purchase of goods other than newspapers), or whether such a levy could encroach upon the Union's taxing powers under Entry 82 of List I (taxes on income other than agricultural income).
In Hoechst Pharmaceuticals, the Supreme Court had upheld a surcharge under the Bihar Finance Act as a sales tax falling within Entry 54 of the State List. Subsequently, in S Kodar, a five-judge bench upheld an additional sales tax under the Tamil Nadu Additional Sales Tax Act, 1970, rejecting the argument that the levy amounted to a tax on income. However, the seven-judge bench in India Cement struck down a cess and surcharge linked to mining royalty, holding that a State could not legislate beyond the fields assigned to it under the Seventh Schedule.
In view of the apparent divergence between these decisions, the Supreme Court referred the question for consideration in 1999. The reference essentially concerns whether a levy imposed on sales or purchases, calculated on the basis of a validly levied sales or purchase tax, is beyond the legislative competence of a State legislature.
During the hearing, the Union Government submitted that the questions had become largely academic following the introduction of the Goods and Services Tax (GST) regime in 2017, although some pending cases might still require adjudication. Solicitor General Tushar Mehta submitted that that the Centre has reservations regarding the correctness of India Cement judgment, which was subsequently overruled by a nine-judge bench. However, Mehta clarified that the Union is not pressing that issue in the present proceedings.
Chief Justice Surya Kant observed during the hearing that India Cement was no longer good law and S Kodar had subsequently been cited with approval. The Bench nevertheless indicated its willingness to examine Kodar independently, including the question whether the nature of a tax, rather than merely the measure used to calculate tax liability, determines legislative competence.